

The burden of proving every cent of your loss falls entirely on your shoulders, not the insurance company’s. When disaster strikes your facility, the clock starts ticking against your business survival. You're likely staring at hundreds of pages of policy language while trying to keep your operations from collapsing. Finding reliable commercial property insurance claim help is often the difference between a full recovery and a permanent closure. It's exhausting to document massive property damage while managing employees and customers. You shouldn't have to fight this battle alone.
We understand that the complexity of modern commercial policies feels like a barrier to your recovery. This guide provides a strategic roadmap for navigating the 2026 insurance landscape. You'll learn how to leverage professional advocacy to level the playing field and secure a settlement that reflects the true value of your loss. We'll break down the documentation requirements, the importance of meeting New Jersey’s strict filing timelines, and the methodical steps needed to minimize business downtime. Order replaces chaos when you have a disciplined plan. Let's start the process of securing your business's future.
Key Takeaways
- Recognize that commercial claims are complex financial negotiations where you bear the full burden of documenting every specific loss.
- Secure expert commercial property insurance claim help to navigate the 2026 landscape and counter insurance carrier lowball estimates effectively.
- Master the immediate mitigation and documentation steps required to protect your business from partial denials and technical policy violations.
- Understand why a public adjuster acts as your strategic shield, providing a necessary buffer between your business and the insurance company’s interests.
- Learn how to navigate New Jersey’s digital filing mandates and strict timelines to ensure your financial recovery remains on track.
Understanding the Complexity of Commercial Property Claims in New Jersey
A commercial insurance claim isn't a simple administrative task. It is a complex financial negotiation where the insurance company’s interests are naturally at odds with your own. Unlike residential claims, the scale of a business loss involves intricate layers of valuation. Property insurance for businesses must account for specialized machinery, vast inventory, and the catastrophic impact of business interruption. These variables make the recovery process significantly more difficult to manage while you’re trying to maintain operations.
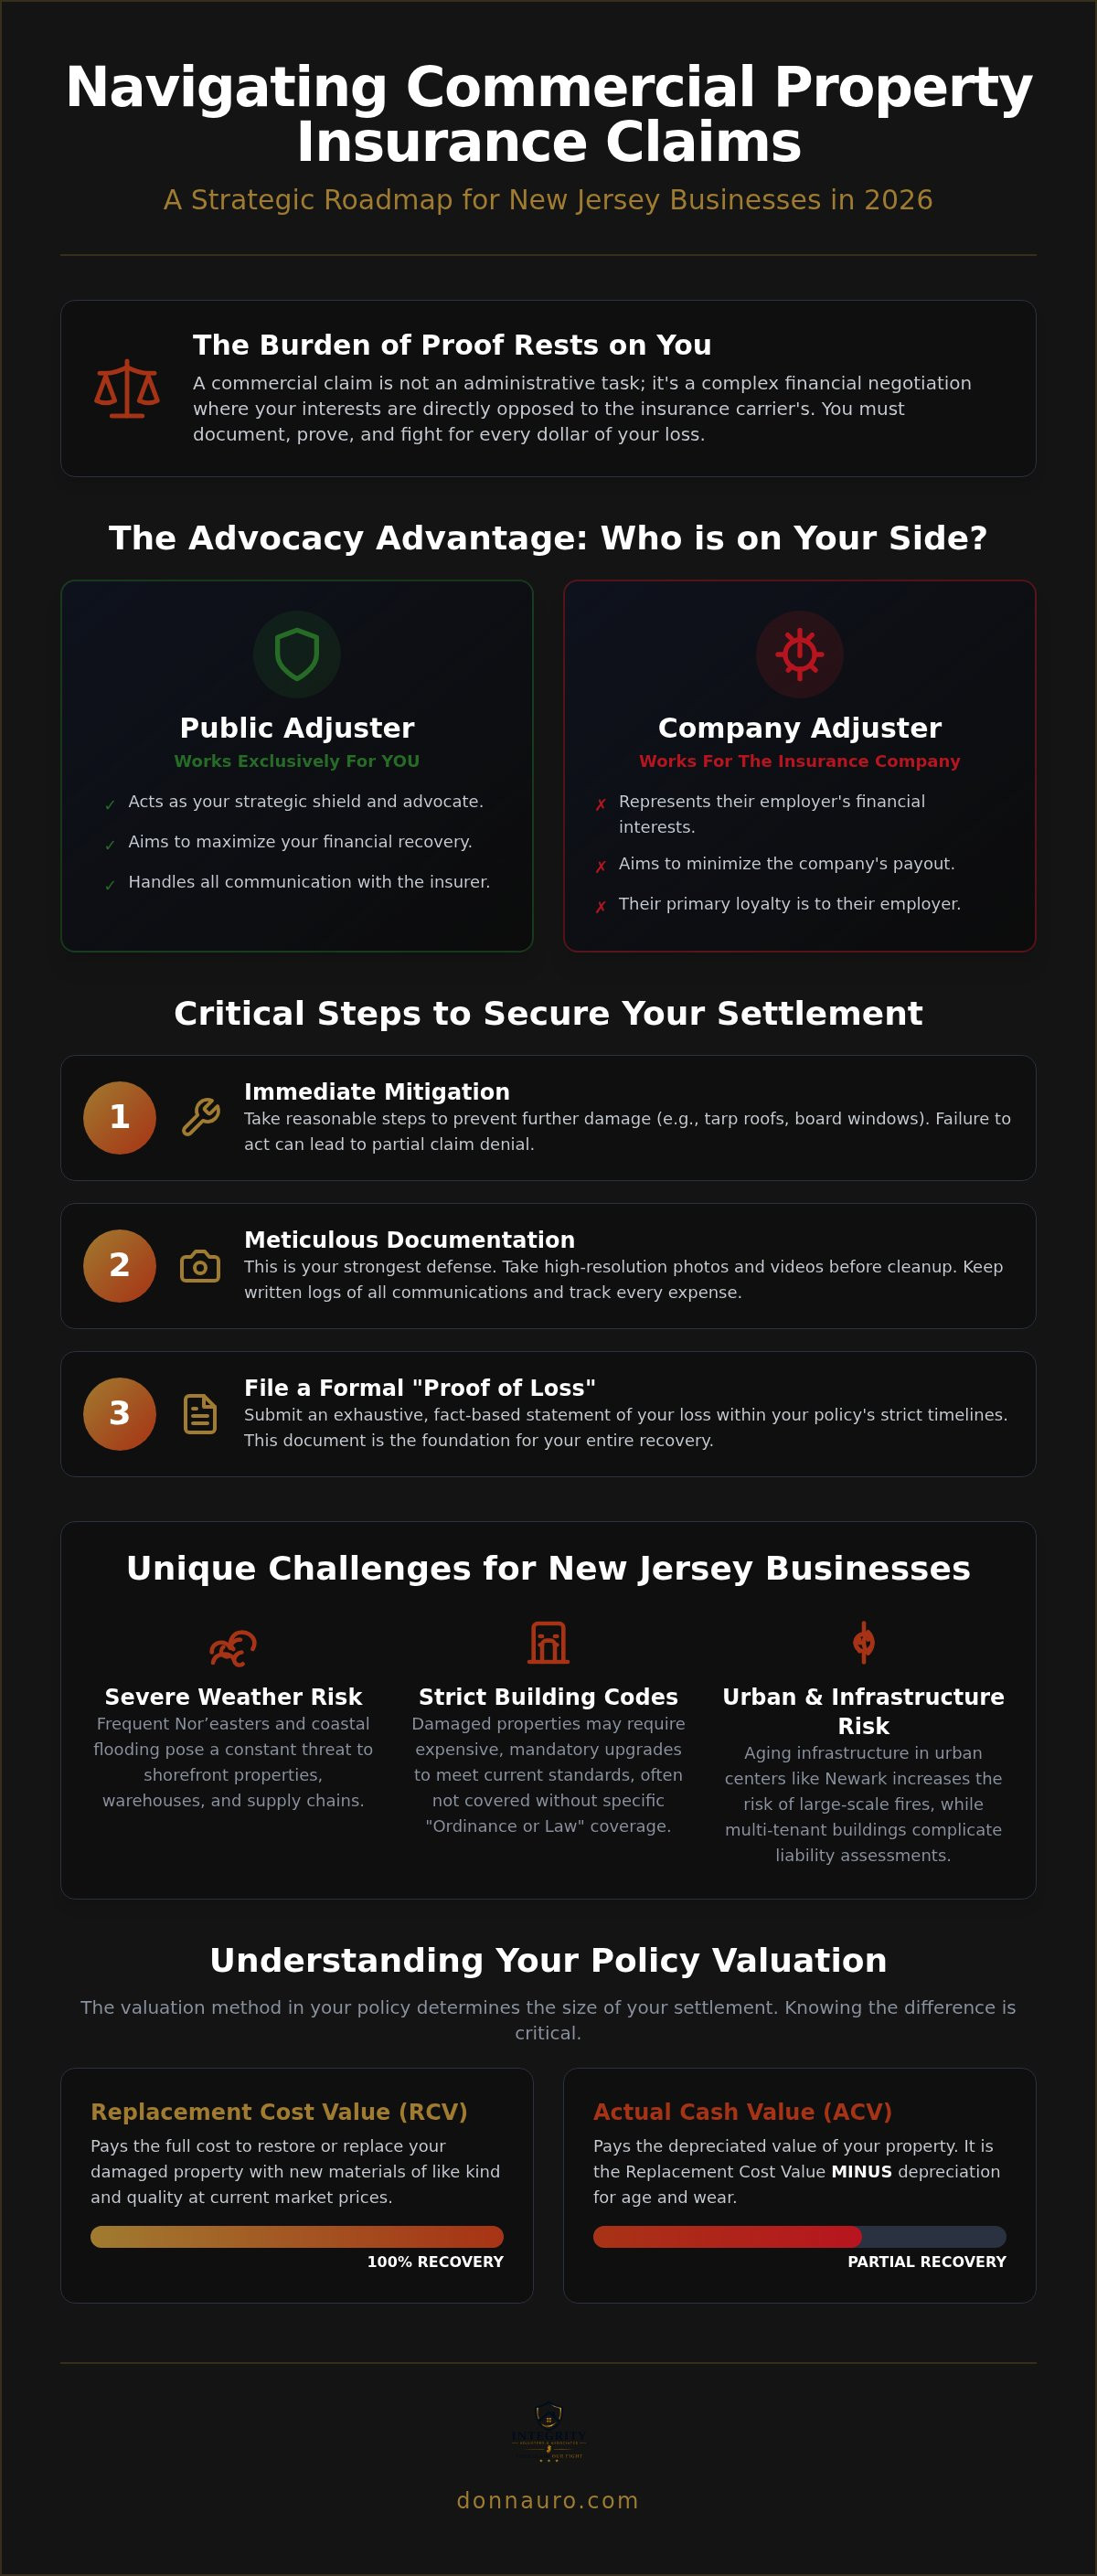
New Jersey businesses face specific environmental and structural risks that complicate these filings. Severe Nor’easters and coastal flooding frequently damage shorefront properties and warehouses. In urban centers like Newark or Jersey City, aging infrastructure increases the risk of large-scale urban fires. These events don't just damage physical walls; they halt your revenue stream and jeopardize your future. You must understand one critical fact: the burden of proof for the loss rests solely on you. The insurance carrier won't find damage for you, nor will they calculate your lost profits out of goodwill. If you don't document the loss with forensic precision, you won't get paid for it. This is why seeking professional commercial property insurance claim help is vital for business survival.
The High Stakes of Business Property Loss
Property damage often triggers a domino effect that reaches far beyond the initial impact. When your doors stay closed, customers quickly find alternatives. Brand reputation suffers when you can't fulfill orders or provide services. If a claim is underpaid or delayed, the resulting financial strain often leads to permanent business closure. To protect your interests, you must understand your policy's valuation methods. Actual Cash Value (ACV) covers the depreciated value of your property, while Replacement Cost pays to restore or replace items with new materials of like kind and quality at current market prices.
Why New Jersey Businesses Face Unique Claim Challenges
New Jersey has some of the strictest building codes in the nation. If a storm damages your facility, you might be required to upgrade the entire electrical or HVAC system to meet current standards. Without "Ordinance or Law" coverage, you'll pay for those mandatory upgrades out of pocket. These hidden costs often devastate a recovery budget. Multi-tenant buildings in New Jersey’s urban corridors add another layer of difficulty. Shared walls and common areas complicate the assessment of liability and damage. A professional property damage assessment ensures that every affected square foot is accounted for in the final filing, acting as a buffer between you and an insurer looking to minimize their payout.
Critical Steps to Secure Your Business Property Insurance Settlement
Your insurance policy is a legally binding contract with strict performance requirements. The moment damage occurs, your primary obligation is mitigation. You must take immediate steps to prevent further loss to remain compliant with your policy terms. This involves boarding up shattered windows, tarping damaged roofs, or extracting standing water. If you fail to act, the insurer may argue that subsequent mold growth or theft was avoidable, leading to a partial or total claim denial. Documentation begins the second you step onto the property.
Meticulous record-keeping is your strongest defense against a low settlement. Every interaction with the insurance company should be documented in writing. Verbal promises from a field adjuster rarely hold weight during the final settlement phase. Keep a detailed log of every phone call, email, and site visit. Every penny spent on the recovery process must be tracked. This includes costs for temporary repairs, security services, and debris removal. Professional commercial property insurance claim help ensures that your "Proof of Loss" is exhaustive, fact-based, and submitted within the required timelines. This document is the formal statement of your loss and serves as the foundation for your entire recovery.
Documenting Physical Damage and Inventory
Visual evidence is non-negotiable in a commercial loss. Capture high-resolution photos and videos from multiple angles before any cleanup begins. Focus on structural damage, equipment, and inventory. Create an itemized list of every piece of machinery, furniture, and stock item affected. Include model numbers, serial numbers, and purchase dates whenever possible. Crucially, do not throw away damaged items before the carrier’s inspection. The insurance company has a right to inspect the physical evidence. If that evidence is in a landfill, you may lose the right to claim those specific items.
Calculating Business Interruption and Extra Expenses
Business Interruption (BI) is often the largest and most undervalued portion of a commercial claim. It is defined as your lost net income plus the expenses that continue despite the damage, such as taxes and key payroll. You are also entitled to "Extra Expenses." These are the costs incurred to minimize the loss and keep the business running, such as renting a temporary office or paying for expedited shipping of replacement parts. The National Association of Insurance Commissioners (NAIC) provides oversight and standards for how these claims should be handled nationally. Accurately calculating these figures often requires forensic accounting to ensure your financial recovery matches your actual losses.
Overcoming Common Obstacles in Business Insurance Recovery
Partial denials represent one of the most frequent hurdles in high-value commercial claims. An insurance carrier may admit that a storm damaged your facility’s roof but deny coverage for the subsequent interior water damage, claiming it resulted from "seepage" or lack of maintenance. This tactic shifts the financial burden of the interior restoration back to your business. You must be prepared to counter these assertions with forensic evidence that links the damage directly to the covered event. If you face a stalemate, seeking professional commercial property insurance claim help ensures you have an advocate who understands how to challenge these "gray area" denials effectively.
Lowball estimates are another systemic issue. Carriers often utilize standardized software that relies on "National Average" repair costs. These figures rarely reflect the actual labor rates and material costs in the New Jersey market. If the insurer's estimate feels insufficient, you have the right to challenge it with independent, local bids. When negotiations over the loss value reach a complete standstill, you can invoke the "Appraisal Clause" found in most policies. This process involves two independent appraisers and a neutral umpire who determine the final settlement amount, often bypassing the need for litigation. You must also remain vigilant regarding carrier delays. New Jersey regulations require insurers to investigate claims within 30 days of receiving a properly completed proof of loss. If they remain unresponsive, a methodical push for updates is necessary to keep your recovery on schedule.
Identifying Hidden Damage Carriers Often Overlook
Insurance adjusters often focus on obvious, visible destruction while ignoring secondary damage that manifests later. After a fire, smoke and soot residue can settle deep within HVAC systems, causing long-term air quality issues and equipment failure. Similarly, windstorms can compromise structural integrity behind finished walls or under floorboards without leaving immediate external signs. For localized issues, it is helpful to review our specific guidance on identifying hidden water damage for NJ insurance claims. Detecting these issues early prevents future out-of-pocket expenses for damage that should have been covered by your initial claim.
The Danger of the "Standard" Carrier Estimate
Carrier-preferred contractors often produce estimates that favor the insurer’s bottom line because they rely on the insurance company for a steady stream of referrals. This creates a conflict of interest that can lead to "scope of work" omissions. Independent, third-party damage assessments are essential to establish an accurate baseline for repairs. Additionally, be wary of how depreciation is applied. Insurers frequently misapply depreciation to commercial assets that are well-maintained or have a long functional life, significantly reducing your actual cash value payout without justification. You deserve a settlement based on current market realities, not arbitrary software averages.
The Advocacy Advantage: Public Adjusters vs. Company Adjusters
Insurance carriers often promote their adjusters as supportive guides. However, a fundamental conflict of interest exists that business owners must recognize. If you are seeking commercial property insurance claim help, you must understand that the adjuster assigned by your carrier is tasked with protecting the insurance company's financial interests, not yours. This systemic bias often leads to overlooked damages and undervalued settlements. Professional advocacy through a public adjuster provides the only dedicated shield for your business during these high-stakes negotiations.
Who Does Your Adjuster Really Work For?
The recovery process involves three distinct types of adjusters, and their loyalties are defined by who pays their fees:
- Staff Adjusters: These are direct, salaried employees of the insurance company. Their primary loyalty is to their employer’s bottom line.
- Independent Adjusters: These are third-party contractors hired by the insurer to handle overflow or specialized losses. While they are not direct employees, they rely on the carrier for continued work, creating a natural incentive to align with the carrier’s valuation.
- Public Adjusters: These are licensed professionals hired exclusively by you, the policyholder. We are the only adjusters in this group with a legal and professional duty to represent your interests alone.
We act as a buffer, managing every aspect of the claim to ensure you receive the full amount you are owed under your policy. By taking control of the communication and documentation, we prevent the carrier from dominating the narrative of your loss.
Leveling the Playing Field in Negotiations
A public adjuster brings technical expertise to the table that most business owners lack. We interpret the dense technical language of your policy, including endorsements and exclusions, to your advantage. While a carrier adjuster might use standardized software to generate a lowball estimate, we use local New Jersey market data to reflect the real cost of reconstruction. We handle the heavy burden of documentation, from itemizing specialized equipment to calculating complex business interruption losses. This methodical approach forces the carrier to address the facts of the loss rather than relying on "National Average" repair costs. Factual accuracy is the foundation of a successful recovery.
The difference in settlement outcomes is often significant. When a business owner manages a claim alone, they are frequently overwhelmed by the administrative requirements and technical jargon. A public adjuster brings order to this chaos. We act as a dedicated shield, ensuring the carrier adheres to New Jersey’s regulatory timelines, such as the 10-day acknowledgment rule and the 30-day investigation requirement. This professional oversight prevents the carrier from dragging out the process or applying unfair depreciation to your assets. Secure professional commercial property insurance claim help to protect your business’s financial future today.
Navigating Your Commercial Claim with Integrity Adjusters & Associates
Integrity Adjusters & Associates provides a firm hand in the turbulent aftermath of a property loss. We act as a dedicated buffer between your business and the insurance carrier. Our focus remains entirely on New Jersey commercial property damage, ensuring that our clients benefit from deep local expertise. We understand the specific pressures of the regional market, from fluctuating reconstruction costs to the nuances of state-specific insurance regulations. When you partner with us, we take control of the insurer’s grueling administrative process. This allows you to focus on your primary responsibility: running your business and maintaining your customer base.
Our approach is rooted in factual integrity and assertive advocacy. We don't rely on guesswork or carrier-provided software. Instead, we build a comprehensive claim file based on empirical evidence and methodical property assessments. This disciplined strategy ensures that every aspect of your loss is documented with forensic precision. Whether you are dealing with a complex industrial fire or a widespread storm loss, our goal is to secure a settlement that reflects the true financial impact on your operations. Reliable commercial property insurance claim help is not just about filing paperwork; it's about providing the stability and expertise needed to survive a catastrophic event.
Commercial Fire and Storm Damage Specialists
Industrial, retail, and warehouse facilities each present unique challenges during a fire loss. A warehouse fire involves complex inventory valuations and potential environmental contaminants, while a retail loss requires a deep analysis of lost sales and brand reputation damage. We tailor our documentation strategies to fit the specific needs of your facility type. We meticulously catalog every piece of specialized machinery and every square foot of affected stock.
New Jersey’s severe storm patterns, including heavy Nor’easters and wind events, often cause structural damage that is difficult to detect. We advocate for a full recovery by identifying these hidden compromises early in the process. Our team looks beyond the surface-level destruction to find the structural shifts and moisture intrusion that lead to long-term issues. We're committed to documenting every detail, ensuring the carrier cannot ignore the true scope of the damage.
Getting Started: Your Path to a Fair Settlement
The first few days following a loss are critical for your financial recovery. An early consultation allows us to set the right tone for the claim from the very beginning. We start by performing a thorough review of your insurance policy. This step is essential to identify all available coverages, including endorsements for business interruption and extra expenses that you might not realize you have. We translate the complex policy language into a clear action plan for your recovery.
You don't have to face a massive institutional system alone. We provide the professional representation needed to level the playing field. By choosing expert advocacy, you ensure that your business has a dedicated shield against underpaid or unfairly denied claims. Contact Integrity Adjusters & Associates for a professional claim review and take the first step toward a full financial recovery.
Secure Your Business’s Financial Recovery
Your business property is more than just a physical asset; it's the foundation of your livelihood. Recovering from a major fire or storm loss requires more than just patience. It demands a methodical approach to evidence and a deep understanding of policy language. The burden of proof rests on your shoulders. Without precise documentation and assertive advocacy, you risk a settlement that fails to cover your true losses. Professional commercial property insurance claim help provides the buffer you need to navigate these complex negotiations successfully.
Integrity Adjusters & Associates specializes in New Jersey commercial advocacy. We focus on expert documentation of fire and storm damage to ensure no detail is overlooked. Our methodical settlement negotiation process is designed to hold carriers accountable to their policy obligations. You don't have to manage this crisis alone while trying to run your company. We bring order to the chaos and act as your dedicated shield against institutional pushback. Take the first step toward a full financial recovery today. Request a Comprehensive Commercial Claim Review from Integrity Adjusters and protect what you've built. Your business's future is worth the fight.
Frequently Asked Questions
What is a public adjuster and how do they help with commercial claims?
A public adjuster is a licensed professional who represents only the policyholder in an insurance claim. We provide essential commercial property insurance claim help by meticulously documenting physical damage and calculating complex financial losses. Our role is to act as a dedicated buffer between your business and the insurance provider. We ensure every technical requirement of your policy is met to secure a settlement that reflects the actual value of your business assets.
Can I file a commercial property insurance claim on my own?
You can file a claim independently, but the process is fraught with risks for business owners. Commercial policies are dense contracts with strict documentation requirements. Without technical expertise, you might overlook hidden damage or fail to calculate business interruption costs correctly. The insurance company's adjuster is looking to minimize the payout. Managing a complex claim while trying to keep your doors open often leads to costly errors or missed deadlines that jeopardize your final recovery.
How much does it cost to hire a public adjuster for a business claim?
Public adjusters typically work on a contingency fee basis. This means we are paid a percentage of the final settlement amount we secure for your business. There are no upfront costs for our advocacy services. This arrangement aligns our interests with yours because our compensation depends on the success of your recovery. We focus on maximizing the claim value through methodical documentation and assertive negotiation to ensure your business receives every cent it is owed.
What should I do if my commercial insurance claim is denied?
If your claim is denied, start by reviewing the formal denial letter to understand the specific policy exclusion the carrier is citing. You have the right to challenge this decision. Gather additional evidence, such as independent damage assessments, to counter their findings. Professional commercial property insurance claim help is often necessary to interpret the policy language and identify if the carrier has misapplied an exclusion or ignored critical facts about the loss.
How long does the commercial property insurance claim process take?
The timeline varies based on the severity of the damage and the complexity of your operations. In New Jersey, insurance companies must acknowledge your claim within 10 days and begin an investigation within that same period. They are generally required to complete the investigation within 30 days of receiving a properly completed proof of loss. High-value commercial claims involving specialized equipment or extensive business interruption can take several months to reach a final settlement.
What is business interruption insurance and how do I claim it?
Business interruption insurance covers the net income your business lost because of a covered peril, along with continuing expenses like taxes and key payroll. To claim it, you must provide forensic financial records that establish your pre-loss revenue baseline. You can also claim extra expenses incurred to keep your business running at a temporary location. We help document these complex financial losses to ensure your claim reflects the true economic impact of the property damage.
Will my insurance rates go up if I hire a public adjuster?
Hiring a public adjuster does not cause your insurance rates to increase. Your premiums are determined by your risk profile, claim history, and broader market trends in New Jersey. The insurance company cannot penalize you for exercising your right to professional representation. Having an expert manage your claim often leads to a more efficient process and a settlement that accurately covers the costs of restoration, which is the primary purpose of your coverage.
Can a public adjuster help if I have already started the claim process?
Yes, a public adjuster can step in at any point during the claim process. Even if you have already received an initial estimate or a partial payment, we can perform a comprehensive review to identify underpaid items or overlooked damage. We often join claims when business owners realize the carrier’s offer is insufficient to cover the actual repair costs. We take over the remaining negotiations and documentation to push for a more equitable final settlement.


