

A mold claim denial isn’t always the end of the process. A Sayreville, NJ, mold damage insurance claim may be covered when mold results from a sudden, covered event, such as a burst pipe or malfunctioning appliance. Standard homeowners policies typically exclude mold linked to long-term moisture and damage from outside flooding, so the cause of the water intrusion and your policy wording matter.
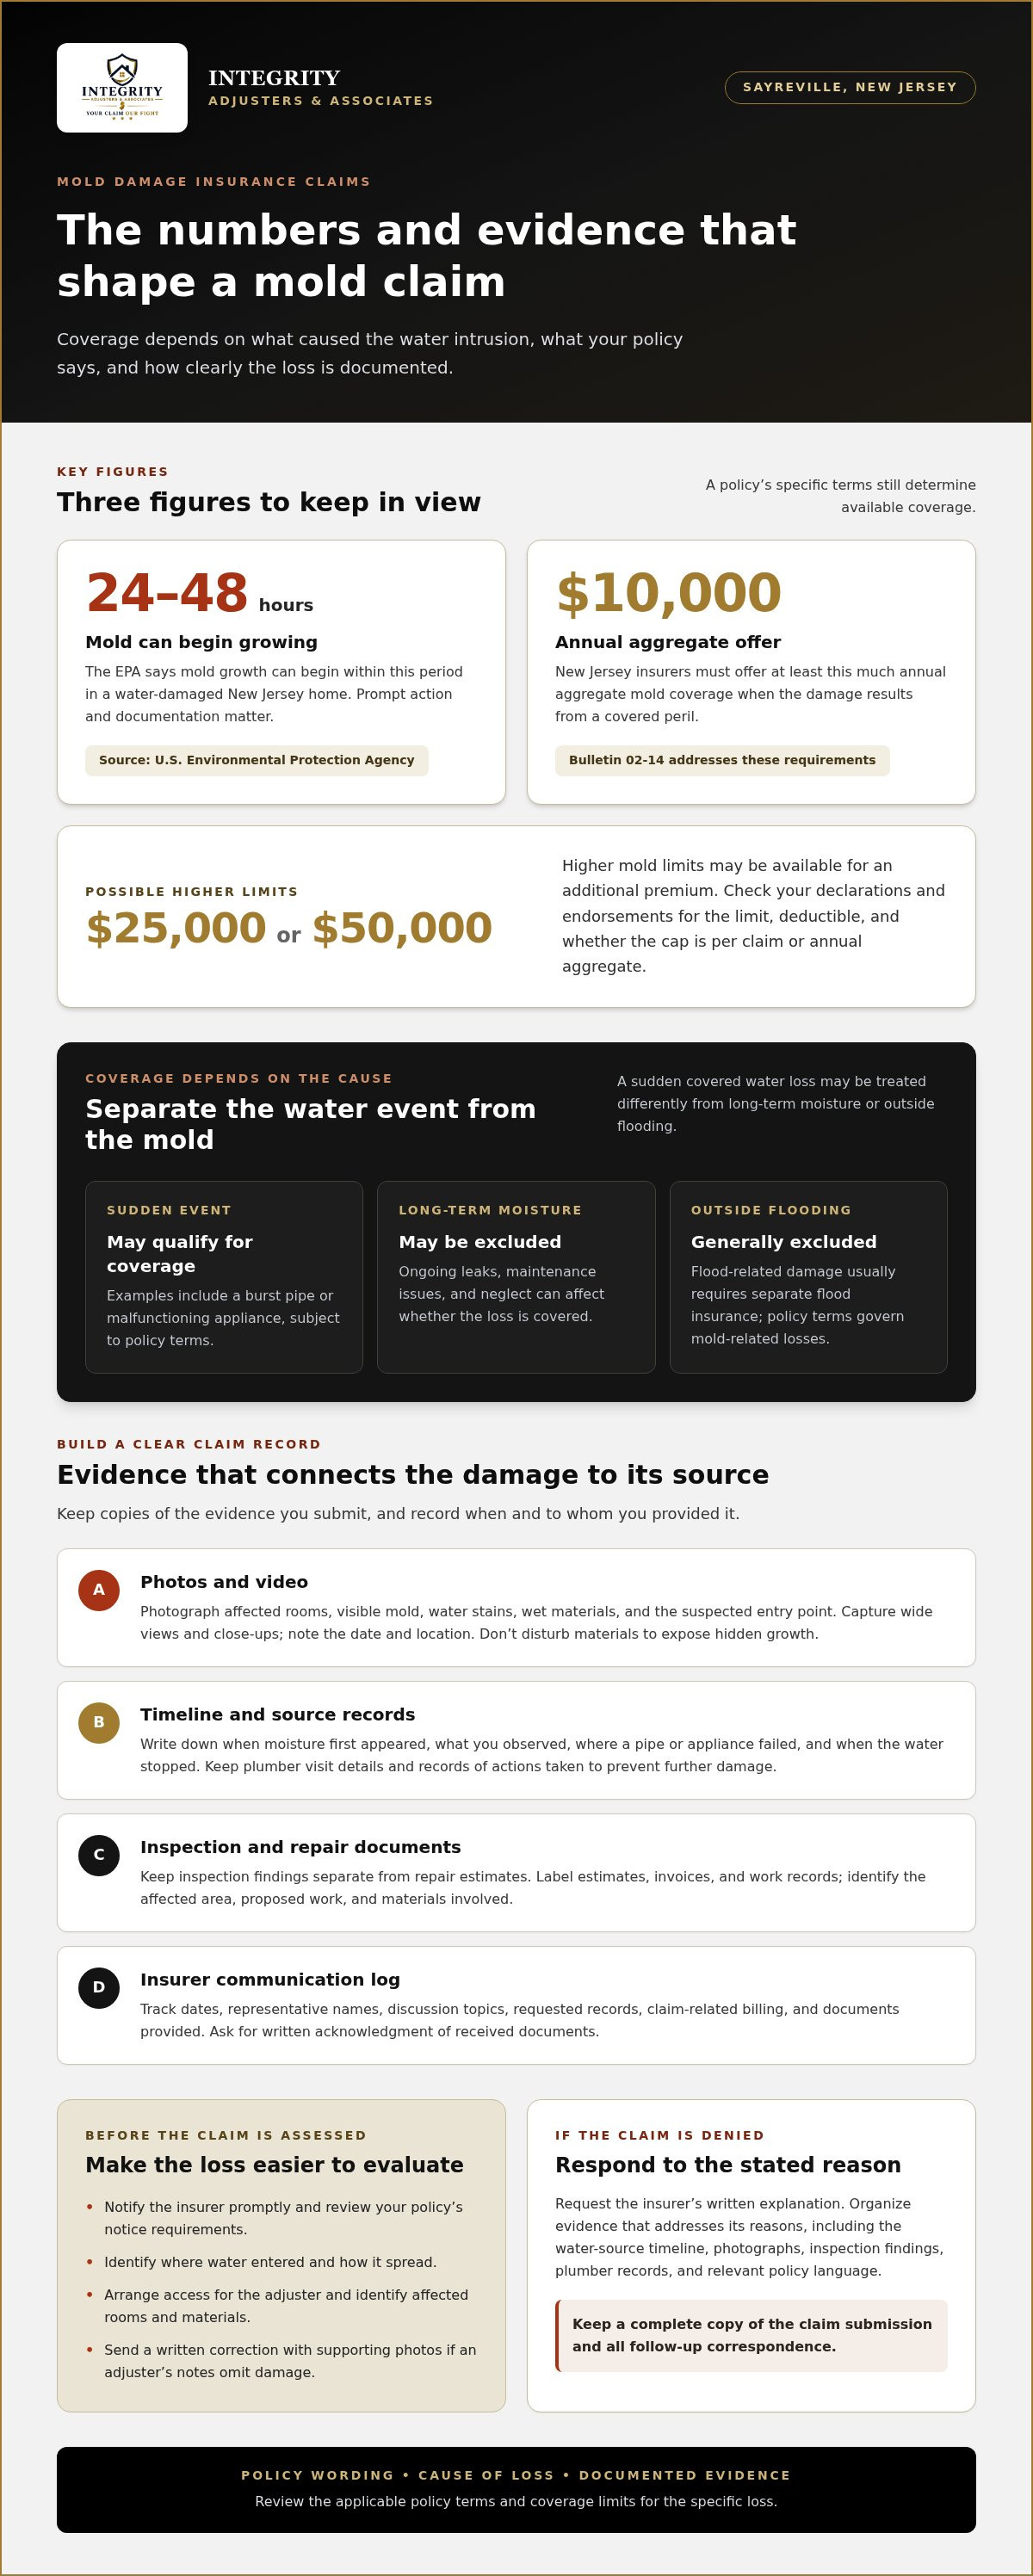
It’s understandable to feel uncertain when water damage turns into mold, especially if an insurer questions whether the loss is covered. Acting promptly matters: according to the U.S. Environmental Protection Agency, mold growth in a water-damaged New Jersey home can begin within 24 to 48 hours. This guide explains how to review your policy, document the mold and the source of moisture, address common exclusions, and respond if your claim is denied. You’ll also learn how an appeal can use organized evidence to challenge an incomplete or disputed assessment.
Key Takeaways
- Read your policy to see how it treats mold caused by a sudden covered water event, and identify any mold coverage limits.
- Build a clear record with photos, videos, moisture evidence, repair documents, and notes from insurer conversations.
- Trace and address the water source, then keep records showing what caused the intrusion and what steps were taken.
- Separate sudden water damage from flooding, ongoing moisture, or maintenance issues when reviewing possible exclusions.
- If your claim is denied, request the insurer’s written explanation and organize evidence that responds to its stated reasons.
Does Homeowners Insurance Cover Mold in New Jersey?
Homeowners insurance may cover mold when it results from sudden, accidental water damage caused by a covered event. Your policy’s cause-of-loss terms, exclusions, and mold limit determine what may be covered.
-
Review Mold Limits and Policy Add-Ons
Find the mold or fungi provision in your declarations and policy endorsements. New Jersey insurers must offer at least $10,000 in annual aggregate coverage for mold damage resulting from a covered peril. Bulletin 02-14 addresses those coverage requirements. Check whether your policy includes the offer, the deductible, and any smaller sublimit for remediation. Higher limits, often up to $25,000 or $50,000 for an additional premium, may be available.
- Separate the water event from the resulting mold damage. A sudden pipe burst or malfunctioning appliance may cause a covered water loss, with mold considered if it follows that covered event. Mold linked to long-term moisture or maintenance issues may be excluded. For example, document whether a supply line failed suddenly or a slow leak went unnoticed. The timeline helps explain how the damage occurred.
- Distinguish interior water damage from surface flooding. Standard homeowners policies typically cover sudden, accidental water damage, while damage from outside flooding is generally excluded. Flood-related damage usually requires separate flood insurance, and the policy terms determine what mold-related losses may qualify. Sayreville’s local context matters: the U.S. Census Bureau estimates the borough’s population at 46,787 residents as of July 1, 2025. Regardless of location, identify where water entered and how it spread.
-
Check Claim Reporting Deadlines
Report the damage to your insurer as soon as you discover it. New Jersey homeowners should notify insurers promptly, because delays can contribute to a denied claim. Review your policy’s notice requirements and record when you first saw water or mold, when you contacted the insurer, and any claim reference. Don’t wait for remediation estimates before giving notice.
- Use your policy, not a general estimate, to determine available mold coverage. Limits vary by contract, and a payout may be capped even when documented damage exceeds the limit. Check whether the limit applies per claim or within an annual aggregate, and whether water repairs have a separate coverage provision. Keep your declarations and endorsement pages with your claim records.
- Inspection costs depend on the assessment’s scope, access to affected areas, and whether testing is included. Compare the written scope with the policy’s covered damage and limit. Keep inspection findings separate from repair estimates so each document clearly supports its part of the claim.
Documenting mold and water damage for an insurance claim
To file in Sayreville, notify your insurer, describe the water event, and submit organized evidence. Keep copies of every photo, report, repair record, and communication related to the loss.
-
Record Mold and Water Damage
Photograph each affected room before moving damaged items, if it’s safe to do so. Take wide views and close-ups of visible mold, water stains, wet materials, and the suspected entry point. Record the date and location for each image. Video can show how damage connects across rooms, but don’t disturb materials to expose hidden growth.
- Write a timeline while the details are clear. Note when you first noticed moisture, what you observed, and any changes since then. For a burst pipe, record where it failed and when the water stopped flowing. Add names and dates for plumber visits, insurer conversations, inspections, and actions taken to prevent further damage.
-
Coordinate Documentation With the Adjuster
Arrange access for the insurer’s adjuster and identify the affected rooms and materials. Share relevant images, your timeline, plumber records, and inspection findings. Keep a copy of what you provide, along with the date and recipient. If the adjuster’s notes omit a damaged area, send a clear written correction with supporting photographs.
- Keep estimates, invoices, and work records in separate, labeled files. A mold remediation estimate should identify the affected area, proposed work, and materials involved. Pair it with photos and inspection findings to provide context. If a report uses terms such as “certified,” keep the document showing the credential and what work it covers.
-
File the Mold Damage Claim
Follow the insurer’s claim process and provide your policy details, date of discovery, suspected cause, and a concise description of the damage. Include a clear evidence index, then submit supporting photos, videos, plumber records, and estimates. Keep the claim number and a complete copy of your submission. Ask for written acknowledgment of documents received.
- Track insurer correspondence and claim-related billing in one log. For each conversation, note the date, representative’s name, topic, and any requested records. Match invoices to the work performed and affected area. Keep payment records and revised estimates together, and flag differences between submitted charges and the insurer’s explanation for follow-up.
Identifying and addressing the source of water intrusion
Trace the water to its source, limit further intrusion, and record each action. The cause helps distinguish sudden water damage from storm flooding or other losses.
- Inspect the affected area and note where water first appeared. Check nearby plumbing, appliance connections, ceilings, windows, and exterior walls for visible signs of entry. A burst pipe may leave a concentrated wet area, while stormwater may enter through a roof opening or foundation. Record what you observe without removing materials that could show the water’s path.
- Stop active water flow if you can do so safely. For a leaking appliance, use its shutoff valve; for a plumbing failure, use the accessible water shutoff. If water continues entering during a storm, document where it’s coming in and protect belongings from further contact where practical. Save receipts for protective materials and note when you used them.
- Photograph the source before repairs change the scene. Capture the damaged pipe, appliance, roof area, window, or other entry point, along with nearby affected materials. Write down when the event began, when you discovered it, and when the flow stopped. These details help connect the sudden event to the resulting water damage and mold.
- Act promptly to reduce lingering moisture. The U.S. Environmental Protection Agency says mold growth in a water-damaged New Jersey home can begin within 24 to 48 hours after flooding. Record water removal, drying, and related work, including dates, invoices, and affected rooms. Keep records distinct from permanent repairs so the insurer can assess mitigation and restoration separately.
- For storm-related intrusion, document both exterior conditions and interior effects. Photograph damaged shingles, broken windows, or water tracks, then show the corresponding ceiling, wall, or floor damage. New Jersey’s severe-storm season runs from June 1 through November 30. A dated record can help show whether wind or rain opened a path for water and support a Sayreville NJ mold damage insurance claim.
- Separate water, fire, and smoke effects in your notes. For example, identify water damage from firefighting separately from smoke residue and direct fire damage. List each affected room and material, then match estimates and invoices to the work described. For a Sayreville NJ mold damage insurance claim, this detail helps distinguish damage sources and makes them easier to assess.
- Seek licensed mold assessment and remediation professionals serving Sayreville, and compare written scopes of work. The New Jersey Department of Health recommends getting multiple estimates from licensed professionals. Ask each estimate to identify affected areas, proposed remediation, and related repairs. Keep assessment findings with your water-source evidence, and don’t treat an estimate as proof of coverage.
- Track every action in a simple timeline, from discovery through drying and repairs. Include who addressed the leak, what work occurred, and which documents went to the insurer. A clear sequence can connect the intrusion, mitigation, and resulting damage. Keep the timeline current as you prepare and update your Sayreville NJ mold damage insurance claim.
Mold exclusions related to neglect, maintenance, humidity, and flooding
Compare your policy’s mold exclusions with the event that introduced moisture. The cause, duration, and flood policy terms can affect whether remediation is covered.
-
Review Mold Exclusions
Read the mold, seepage, and maintenance provisions, then compare them with the property’s moisture history. New Jersey homeowners’ policies generally exclude mold caused by neglect or long-term moisture problems. A slow leak beneath a sink may be treated differently from a sudden pipe failure. Keep maintenance records and repair dates so the insurer can assess the timeline.
-
Check Flood Insurance and Mold Coverage
Review your separate flood policy if outside water entered the home. Standard homeowners insurance generally excludes flood damage, while flood-related mold usually requires separate flood insurance. NFIP coverage excludes mold or moisture damage that could have been avoided or wasn’t caused by flooding. Compare the policy wording with the actual entry point and the steps taken to limit moisture.
-
Consider Common Local Flooding Causes
Identify whether water came from outside flooding, storm-related entry, or an interior plumbing failure. Sayreville experienced severe flooding during Superstorm Sandy in October 2012. That history makes it important to document the specific cause of each loss, not assume all water damage falls under the same insurance policies. Note where water entered and which rooms it affected.
- Distinguish a covered sudden event from gradual dampness. A broken pipe, appliance failure, or roof opening may create a distinct timeline, while recurring moisture can point to maintenance or ventilation issues. Record when the problem began, what you observed, and what repairs followed. This evidence helps clarify whether mold resulted from a single event or prolonged exposure.
- Address indoor humidity as part of prevention and documentation. The recommended target is below 60% relative humidity. Note persistent condensation on windows, damp bathroom surfaces, or repeated moisture in a basement. These observations don’t replace the policy analysis, but they help show whether conditions continued after the original water event and whether steps were taken to limit further growth.
- Build a record of the cause and your response. Include photos of the entry point, cleanup dates, maintenance records, and invoices for water removal or remediation. For stormwater, document exterior and interior evidence separately. An organized file can distinguish flooding from plumbing damage and show whether moisture could have been avoided after discovery.
Appealing a denied mold insurance claim
A denial doesn’t end your options: New Jersey homeowners can appeal a denied mold claim. Start with the insurer’s stated reason, then respond with evidence that addresses it.
- Request the denial and its explanation in writing. Identify the policy provisions the insurer relied on, including any mold exclusion, water-damage condition, or coverage limit. Keep the date you received the decision and the claim reference with your records. A written explanation gives you a clear basis for challenging the insurer’s reasoning.
- Break down each reason for denial and match it with relevant evidence. If the insurer says basement mold resulted from ongoing moisture, gather records showing when you discovered the water, what caused it, and what repairs followed. If the dispute concerns flooding, provide evidence showing where the water entered. Address each point directly instead of resending an unorganized file.
- Build a timeline from discovery through mitigation. Include photographs, plumber records, inspection findings, invoices, and insurer communications. The U.S. Environmental Protection Agency says mold can begin growing in a water-damaged New Jersey home within 24 to 48 hours after flooding. Dated records of drying or water removal can show what actions followed discovery and when.
- Submit a focused appeal through the insurer’s stated process. Include the claim number, denial date, a concise explanation of why the decision should be reconsidered, and labeled supporting documents. For example, if the denial attributes mold to neglect, pair repair records and dated photographs with evidence of the sudden water event. Keep a complete copy and note when you submitted it.
- Track the appeal and any new requests in writing. Record the representative’s name, each conversation date, and the documents requested or provided. If an adjuster’s assessment omits a damaged room or conflicts with an inspection report, explain the discrepancy and attach relevant evidence. Keep your tone factual and make each response traceable to the claim file.
- Review deadlines before deciding what to do next. Your policy may set a contractual period of one or two years after the loss occurs or is first discovered to file a lawsuit against the insurer. Read the exact wording and note any stated dates; an appeal does not automatically replace a separate contractual deadline. In most states, insurers must explain a denial in writing and advise that the limitation period is running.
- Keep the appeal focused on coverage, cause, and documented damage. Separate mold remediation from unrelated repairs, and explain how each requested amount relates to the loss. If the insurer upholds its denial, preserve all correspondence and evidence. A complete record helps you understand the decision and assess your remaining options.
Integrity Adjusters & Associates: Residential Water Damage Claim Support
Integrity Adjusters & Associates supports New Jersey homeowners with residential water damage claims, including losses where mold follows water intrusion. The firm helps document property damage and assemble a comprehensive claim for presentation to the insurer. This support can help organize the cause, affected areas, and repair records.
Gather your policy documents, photographs, inspection findings, invoices, and insurer correspondence. Integrity Adjusters & Associates helps ensure property losses are accurately documented and presented as part of the claim. Its support focuses on claim documentation and advocacy, not physical restoration or repair.
For help organizing a residential water damage claim in New Jersey, contact Integrity Adjusters & Associates.
Move Forward With a Clear Claim Strategy
Turn the information you’ve gathered into a focused decision: what the insurer accepted, what remains disputed, and which records address the gap. For a Sayreville, NJ, mold damage insurance claim, keep your next communication centered on the evidence and the specific policy language at issue. A concise, organized response keeps the discussion tied to the facts.
If your claim is difficult to organize or present, Integrity Adjusters & Associates can help document property losses and build a comprehensive claim for the insurer. The firm can help organize records and clarify how the reported damage fits together. You remain the decision-maker throughout the process.
Contact Integrity Adjusters & Associates to discuss support with your property claim. Take the next step with a clear record and a steady plan.
Frequently Asked Questions
Does homeowners insurance in Sayreville, NJ cover mold damage?
Mold may be covered when it results from a sudden water event covered by your policy, but the policy’s mold terms and limit matter. For example, mold after an accidental appliance leak may be treated differently from mold following outside flooding. Check your declarations and endorsements for the applicable limit, then compare them with the cause and affected property documented in your claim.
What causes of mold damage are covered or excluded by New Jersey homeowners insurance?
A sudden, accidental event, such as a pipe or appliance failure, may support coverage if your policy covers the resulting water damage. Mold linked to neglect, ongoing moisture, or maintenance problems is generally excluded. Standard homeowners insurance typically excludes outside flooding, which usually requires separate flood coverage. If the cause is disputed, a timeline of leaks, repairs, and discovery can help clarify what happened.
What evidence and documents are needed for a mold insurance claim?
Gather dated photos and videos, a written timeline, plumber or appliance-service records, inspection findings, repair estimates, invoices, and insurer correspondence. Label images by room and describe what each shows. For example, pair a photo of a stained basement wall with a record identifying a nearby plumbing issue. Keep copies of submitted materials and note when each item was sent.
How do insurers calculate mold damage claim payouts and coverage limits?
Insurers review the covered cause, documented damage, policy provisions, and applicable mold limit. A policy may cap mold-related payments even when estimated remediation costs exceed that amount. Your claim file should distinguish mold work from other water repairs and connect each estimate to affected areas. Compare the insurer’s calculation with the policy language and submitted scope, noting omitted damage or charges.
What should I do after water damage to prevent mold and protect my claim?
Stop the water source if safe, protect belongings from additional exposure, and arrange water removal and drying. The U.S. Environmental Protection Agency says mold can begin growing in a water-damaged New Jersey home within 24 to 48 hours after flooding. Photograph conditions before cleanup when safe, save work records, and notify your insurer promptly while following the policy’s claim instructions.
Can an insurer deny a mold claim for gradual leaks or poor maintenance in New Jersey?
Yes. New Jersey homeowners’ insurance generally excludes mold caused by neglect or long-term moisture problems. A denial may depend on whether records show a sudden failure or signs of an unresolved leak. For example, dated plumbing invoices and earlier repair notes can help establish the leak’s history. Review the insurer’s written explanation and your policy wording to see which facts it relied on.
How can I dispute a denied or underpaid mold damage claim in New Jersey?
Ask the insurer for its written explanation, then respond to each stated reason with relevant records. If an estimate omits a room, submit a labeled photo and inspection details for that area. If the dispute concerns the cause, provide a concise timeline and repair documents. Keep copies of the appeal and correspondence, and track any contractual deadlines stated in your policy.


