

Your insurance company's adjuster isn't there to find every dollar your association is owed. They are there to close a file. Managing a multi-family property loss in 2026 is an exhausting balancing act. You're caught between residents demanding immediate repairs and an insurer offering a settlement that barely covers the drywall. The confusion between Master Policy coverage and individual HO-6 responsibilities can stall progress for months while structural damage goes unaddressed.
It's a high-stakes situation that requires a disciplined navigator. Hiring a dedicated condo association insurance claim adjuster changes the dynamic immediately. You gain a strategic ally who documents the full scope of structural damage and common area losses. This ensures the settlement actually covers the full cost of professional restoration rather than just a quick patch. You don't have to guess if the insurance company's estimate is fair. You'll have the evidence to prove it isn't.
This article explains how to handle complex apartment and condo building claims under new 2026 lending and insurance regulations. We will show you how to bridge the gap between policy types and secure the funding your board needs to protect the community’s assets without the usual conflict.
Key Takeaways
- Understand the critical boundary between Master Policy and unit owner coverage to prevent financial gaps in structural recovery.
- Discover how a specialized condo association insurance claim adjuster uses forensic evidence to challenge lowball insurer estimates.
- Learn why the insurance company's initial offer is often a financial floor rather than a full restoration settlement.
- Identify immediate mitigation steps that protect the association's liability while preserving the physical integrity of the claim.
- Master the process of building a documented, fact-based claim that minimizes friction between the board and your residents.
The Unique Complexity of Apartment and Condo Association Insurance Claims
Managing a property loss for a multi-family building isn't just a larger version of a standard residential claim. It is a legal and structural puzzle. When a fire or major water leak occurs, the interests of dozens or hundreds of residents collide with the responsibilities of the board. A standard residential adjuster often lacks the training to parse these layers. They might overlook how damage in one unit compromises the structural integrity of the entire stack. This is where a specialized condo association insurance claim adjuster becomes essential. They act as a professional buffer, ensuring that the association's collective interests are protected against an insurer that wants to minimize the payout.
New Jersey associations operate under specific bylaws that dictate exactly where the association’s responsibility ends and the unit owner’s begins. These documents are the blueprint for your recovery. If your adjuster doesn't master these bylaws, the association risks paying for repairs that the insurance carrier should have covered. Understanding What is a Public Adjuster? helps boards realize they need an advocate who specifically handles these multi-unit entities rather than a generalist who treats the building like a row of independent houses.
Master Policy vs. Unit Owner Coverage
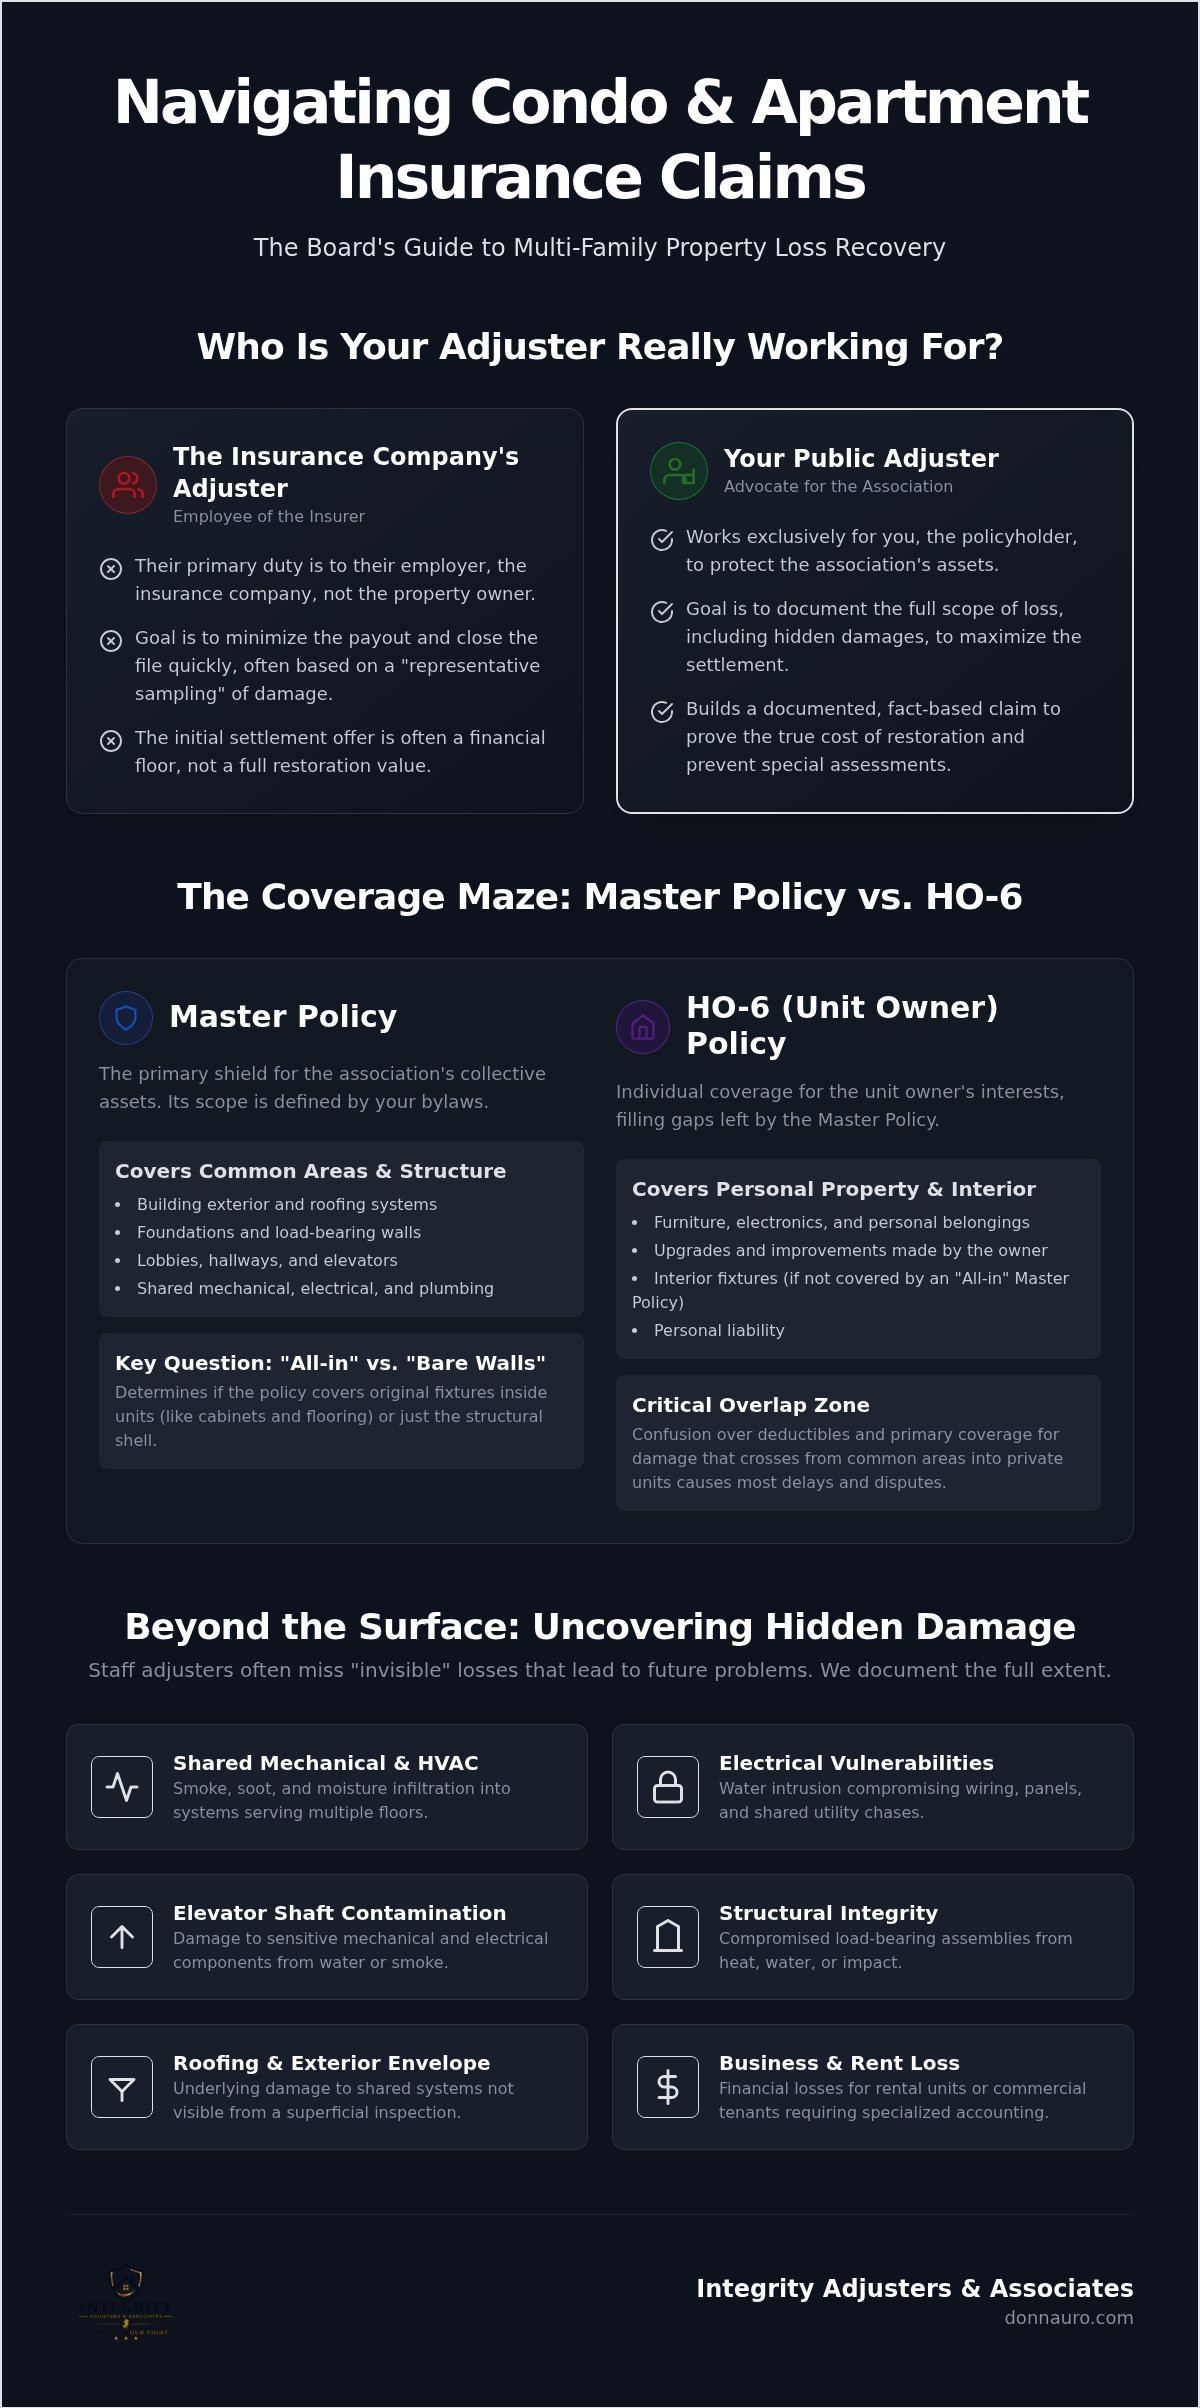
The friction between the Master Policy and individual HO-6 policies is the most common cause of claim delays. In New Jersey, coverage typically falls into two categories. "All-in" policies cover the original installations within units, while "walls-in" or "bare walls" policies only cover the building's shell. A condo association insurance claim adjuster meticulously reviews the association’s governing documents to determine which policy is primary for every damaged square foot. The Master Policy serves as the primary shield for the association’s assets. Without this clarity, residents and the board often end up in conflict over who pays the deductible for common area damage that bleeds into private living spaces.
Common Area Damage and Structural Integrity
Structural damage in multi-story apartment blocks is rarely localized. Water travels through utility chases, and smoke infiltrates shared ventilation systems. What looks like a cosmetic stain in a hallway often points to a compromised mechanical room or a failing roof assembly. We focus on documenting the "invisible" losses that staff adjusters often ignore:
- Mechanical and HVAC systems serving multiple floors.
- Elevator shaft contamination and electrical vulnerabilities.
- Load-bearing assemblies affected by heat or moisture.
- Shared roofing systems and exterior envelopes.
Don't accept a settlement that only covers paint and carpet. In large complexes, "cosmetic" fixes often hide deep structural issues that lead to expensive special assessments later. We ensure every documented loss reflects the actual cost of professional restoration.
Why Multi-Family Properties Need a Specialized Public Adjuster
Multi-unit properties present unique logistical hurdles that standard residential claims don't face. When damage impacts fifty units simultaneously, the insurance company's adjuster often performs a "representative sampling" rather than a total inspection. This approach leaves thousands of dollars on the table because it ignores unit-specific variations. A specialized condo association insurance claim adjuster manages the exhaustive process of inspecting every single affected space. They document individual losses while tracking how they impact the building's shared infrastructure. This methodical approach is supported by the National Association of Public Insurance Adjusters, which emphasizes the need for dedicated policyholder advocacy in complex losses.
Forensic evidence is the foundation of a successful settlement. We don't just look for visible damage; we identify the source and the full extent of the intrusion. For associations with rental units or commercial tenants on the ground floor, documentation must include business interruption and loss of rent. These financial losses are often as significant as the physical damage but require specialized accounting to prove to an insurer. Our role is to bring order to this chaos, ensuring that every financial impact is quantified and documented.
Building a Comprehensive Evidence Portfolio
We use advanced technology to find what the naked eye misses. Moisture mapping and thermal imaging reveal water trapped behind fire-rated assemblies or within floor slabs. This data prevents the insurer from offering a "lump sum" settlement that fails to address hidden mold or rot. Integrity Adjusters & Associates provides detailed line-item estimates. These documents break down every nail, board, and hour of labor required for restoration. It creates a claim profile that is difficult for carriers to dismiss because it's based on indisputable physical facts.
Advocating for Fair Settlements in New Jersey
New Jersey property law and insurance regulations involve strict timelines. Missing a deadline for a proof of loss can jeopardize the entire claim. We act as your strategic ally and buffer. We handle the aggressive questioning from the carrier's adjusters so your board doesn't have to. Hiring a condo association insurance claim adjuster ensures that your board isn't forced to accept the first low offer. If you are managing a property with shared retail spaces, you may also need Commercial Property Insurance Claim Help: A Guide to Business Advocacy in 2026 to navigate those specific policy nuances. Our local expertise ensures your association remains compliant with NJ-mandated response times while fighting for a settlement that covers professional restoration. Working with a dedicated advocate allows your board to focus on community management while we focus on the recovery.
Public Adjuster vs. Insurance Company Adjuster: The Conflict of Interest
Many condo boards assume the adjuster sent by the insurance company is a neutral arbiter of facts. This is a dangerous misconception. That individual is either a direct employee or a third-party contractor hired by the insurance carrier. Their primary loyalty is to the company paying their salary. While they are expected to be professional, their performance is often measured by how well they control costs and limit "claim leakage." This structural bias means their initial estimate should be viewed as a financial floor, not a ceiling. It represents the minimum amount the insurer believes is necessary to satisfy the policy, not the actual cost of a full restoration.
A condo association insurance claim adjuster provides the necessary counterweight. Unlike the company's representative, a public adjuster has undivided loyalty to the policyholder. This distinction is critical in complex multi-party claims where common areas and private units are both affected. You need an advocate who isn't looking for ways to exclude coverage but is instead searching for every documented detail to justify a full settlement. We act as a strategic buffer, ensuring the board isn't pressured into a settlement that fails to address the community's long-term needs.
The Financial Reality of Claims
Insurance companies are businesses driven by profit margins. Staff adjusters are trained to follow internal guidelines that prioritize cost-efficiency over comprehensive restoration. They might suggest cleaning a smoke-damaged hallway when the industry standard requires full replacement to ensure resident safety. Public adjusters focus on claim accuracy. We identify the true cost of labor and materials in 2026, which often exceeds the outdated pricing software used by many carriers. Your insurance company’s adjuster works for their bottom line, while we work for yours.
Technical Expertise and Representation
The depth of a public adjuster’s inspection is significantly more exhaustive. While a company adjuster might spend two hours on-site, we spend days meticulously documenting every affected square inch. This level of detail is a requirement for high-value properties. If your association includes commercial spaces, you may face even more complex hurdles, similar to those found when hiring a Public Adjuster for Office Building Damage: Maximizing Your Commercial Claim in 2026.
Having a strategic ally in settlement negotiations changes the power dynamic. We speak the language of the insurance industry and understand the nuances of state insurance regulations that protect your rights as a policyholder. We don't just ask for more money; we provide the forensic evidence and line-item documentation that makes a higher settlement undeniable. This representation acts as a shield, preventing the board from being pressured into a premature or inadequate agreement.
Steps to Take After Damage Occurs in Your Apartment Building
The moments following a fire, major leak, or storm are chaotic. Decisions made in the first 48 hours dictate the success of a multi-million dollar claim. There is a critical window for hiring a condo association insurance claim adjuster before the insurance company issues its first offer. Engaging an expert early prevents the carrier from setting an artificially low financial baseline that becomes difficult to challenge later. Your primary goal is to stabilize the property while building a foundation of evidence that the insurer cannot ignore.
Immediate Mitigation and Safety
Most association policies include a "Duty to Mitigate." This requires the board to take reasonable steps to prevent further loss. If a roof is compromised, it must be tarped. If a pipe burst, standing water must be extracted immediately to prevent mold growth. However, you must secure the property without destroying the evidence required for the claim. Take high-resolution photos and video of the damage before any temporary repairs begin. Keep every receipt for emergency services and materials. These costs are typically reimbursable, but only if they are documented as necessary for property stabilization. Do not allow contractors to begin permanent restoration until the insurance company’s representative and your own adjuster have completed a joint inspection.
Organizing the Association’s Response
Centralize all documentation and correspondence immediately. Designate one board member or the property manager as the sole point of contact for the insurer to avoid conflicting statements. Create a unit-specific damage log and ask residents to submit written descriptions and photos of damage within their private spaces. This prevents "claim drift," where damage is forgotten or misattributed weeks after the event. Communicating effectively with unit owners is vital to manage expectations and reduce the pressure on the board to rush into an inadequate settlement.
If the building houses commercial tenants or shared retail spaces, the board must also consider the broader economic impact. Review our guide on Business Interruption Insurance Claim Help: A Guide to Economic Recovery to understand how to document lost revenue during the restoration period. Organizing these financial records early ensures they are included in the initial claim package rather than filed as an afterthought.
Don't let the insurance company's timeline dictate your community's recovery. If your building has suffered significant damage, contact Integrity Adjusters & Associates to ensure your evidence is preserved and your claim is filed correctly from day one.
Integrity Adjusters: Your NJ Advocate for Multi-Family Property Losses
Integrity Adjusters & Associates serves as a strategic partner for New Jersey condo associations and apartment managers. We bring order to the chaos of property loss. Our team acts as a disciplined navigator, guiding boards through the intricate maze of master policies and insurance carrier demands. We provide a professional buffer that protects board members from the direct pressure of insurance adjusters. This steady presence allows your association to focus on resident safety and community stability while we handle the technical execution of the claim. We act as a dedicated shield for your community against complex institutional systems.
Transparency and factual integrity are the pillars of our practice. We don't use flowery language or vague promises. Instead, we rely on a methodical approach that prioritizes documentation and evidence. Our goal is to ensure that your settlement reflects the true cost of restoration, not just a surface-level repair. We are your dedicated advocate in a system that often prioritizes the insurer's bottom line over the policyholder's recovery.
Methodical Documentation for NJ Claims
We translate structural damage into professional claim language that insurers respect. In the New Jersey market, local expertise is not optional. It is a requirement for accuracy. We understand how to coordinate with NJ-specific bylaws and state regulations to ensure every loss is recorded correctly. Our process involves detailed inspections that track damage from the roof down to the mechanical rooms. We don't accept the "lump sum" offers that often leave associations with massive financial gaps. By using a condo association insurance claim adjuster from our firm, you ensure that every line item is justified by forensic data. We document the facts so the insurance company cannot ignore the reality of your loss.
Contact Us for a Comprehensive Claim Review
Your association’s financial health depends on a fair insurance settlement. Don't let an inadequate initial offer force a special assessment on your residents. We encourage a proactive review of your current claim status. Whether you are in the immediate aftermath of a crisis or struggling with a stalled claim, our firm provides the strategic advocacy required for recovery. We remain focused on the facts and the next logical action to move your claim forward. Our methodical approach ensures that your board has the documentation needed to make informed decisions. Contact Integrity Adjusters & Associates to gain a strategic ally who will fight for your association's interests with precision and professional authority.
Restore Your Community’s Stability with Expert Advocacy
Navigating a multi-family property loss requires more than just patience. It demands a technical understanding of the friction between Master Policies and unit owner coverage. You've seen how forensic evidence and methodical documentation of structural property losses are the only ways to challenge an insurer’s "representative sampling." Relying on the insurance company’s staff adjuster often leads to settlements that fail to cover the actual costs of professional restoration in 2026.
A specialized condo association insurance claim adjuster acts as your disciplined navigator through this institutional complexity. We provide the NJ-based public adjusting advocacy needed to protect your board from the pressure of residents and the cost-cutting measures of insurance carriers. As a protective expert for both commercial and residential claims, we ensure your association’s interests remain the priority throughout the process. You don't have to manage this crisis alone or guess at the accuracy of an estimate.
Secure a fair settlement for your association with Integrity Adjusters & Associates. Our team is ready to bring order to your claim and ensure a clear path to full recovery. We are here to provide the steady hand your community needs to move forward with confidence.
Frequently Asked Questions
What is the difference between a condo association adjuster and a regular insurance adjuster?
A condo association insurance claim adjuster, also known as a public adjuster, works exclusively for the association board. A regular insurance adjuster is either a staff employee or a contractor hired by the insurance carrier to protect their financial interests. While the insurer's adjuster focuses on cost control, a public adjuster focuses on claim accuracy and comprehensive documentation of all structural and common area losses.
When should our HOA hire a public adjuster for an insurance claim?
You should hire a public adjuster immediately after a significant loss occurs, ideally before the insurance company makes its first offer. Early involvement ensures that evidence is preserved and the claim is framed correctly from day one. This is especially critical in 2026 due to stricter lender requirements for "Full Reviews" of association financials and insurance coverage following significant property damage in multi-family complexes.
Can a public adjuster help if our apartment building claim has already been denied?
Yes, a public adjuster can review a denied claim to determine if the insurer’s decision was based on an incomplete assessment or a misinterpretation of the Master Policy. We perform a methodical review of the forensic evidence and the association’s governing documents. If the denial was improper, we build a documented case to reopen the claim and advocate for the settlement your association is legally entitled to receive.
How much does a condo association insurance claim adjuster cost in New Jersey?
Public adjusters in New Jersey typically work on a contingency fee basis. This means the fee is a percentage of the final settlement recovered from the insurance company. This arrangement ensures that the adjuster's interests are aligned with the association’s goal of securing a fair and comprehensive payout. Boards should review the specific fee structure during the initial consultation to ensure it meets New Jersey’s regulatory standards for reasonableness.
Does the public adjuster handle claims for individual unit owners as well?
Our primary focus is representing the association board to handle Master Policy claims for common areas and structural elements. Individual unit owners typically need to file their own claims through their HO-6 policies for personal property and interior finishes. However, we ensure that the Master Policy claim is coordinated correctly so that no gaps exist between the building's structural recovery and the unit owners' individual repair efforts.
How long does the condo insurance claim process typically take with an adjuster?
The timeline varies based on the complexity of the damage and the responsiveness of the insurance carrier. Large-scale multi-family claims can take several months to resolve fully. Hiring a condo association insurance claim adjuster speeds up the process by ensuring all documentation is submitted correctly the first time. We manage the communication flow and hold the insurer to specific New Jersey timelines for claim responses and settlement offers.
What happens if our Master Policy and the unit owner policies overlap during a claim?
Overlaps or gaps between the Master Policy and HO-6 policies are frequent sources of conflict. We meticulously review the association’s bylaws and CC&Rs to determine which policy is primary for specific structural components. This is vital in 2026, as shifting insurance responsibilities and new lender guidelines have made precise policy coordination essential to avoid special assessments or resident litigation during the restoration of the building.
Is a public adjuster the same as an insurance lawyer?
No, a public adjuster is a licensed insurance professional specializing in damage appraisal and claim negotiation, not a legal representative. We focus on the technical and forensic documentation of property loss to build a factual case for the insurer. While we advocate for your interests, we don't provide legal advice or represent associations in a court of law. If a claim requires legal action, the board would need separate counsel.


