

Your insurance adjuster is not there to ensure your business recovers every lost dollar. They represent the carrier's interests, and their primary goal is to settle the file for the lowest defensible amount. When you file a Paterson NJ commercial fire claim, you are dealing with more than just physical damage. You are navigating the City of Paterson’s specific enforcement of the New Jersey Uniform Construction Code and mandatory safety inspections. It is a high-stakes environment where a single error in your initial documentation can lead to a significant underpayment or a prolonged claim denial.
We know the pressure of watching your revenue vanish while your doors stay closed. Documenting business interruption losses is notoriously difficult, and the fear of an unfair settlement is a reality for many local owners. You deserve a recovery that reflects the true value of your loss. This guide outlines how to secure a settlement covering full replacement costs and minimize your downtime through expert claim management. We will show you how professional advocacy acts as a buffer between you and the adjuster, ensuring your business gets the financial support it needs to reopen and thrive.
Key Takeaways
- Secure your property immediately and obtain the official fire report to establish a factual foundation for your loss.
- Navigate Paterson's unique building codes by understanding how Law and Ordinance coverage protects older industrial properties.
- Protect your revenue by accurately documenting business interruption and soft costs during a Paterson NJ commercial fire claim.
- Identify hidden fire damage, such as soot in HVAC systems, that standard company adjusters often overlook.
- Leverage professional advocacy to handle negotiations and ensure your settlement covers the full cost of replacement.
Critical Immediate Actions for a Paterson Commercial Fire Claim
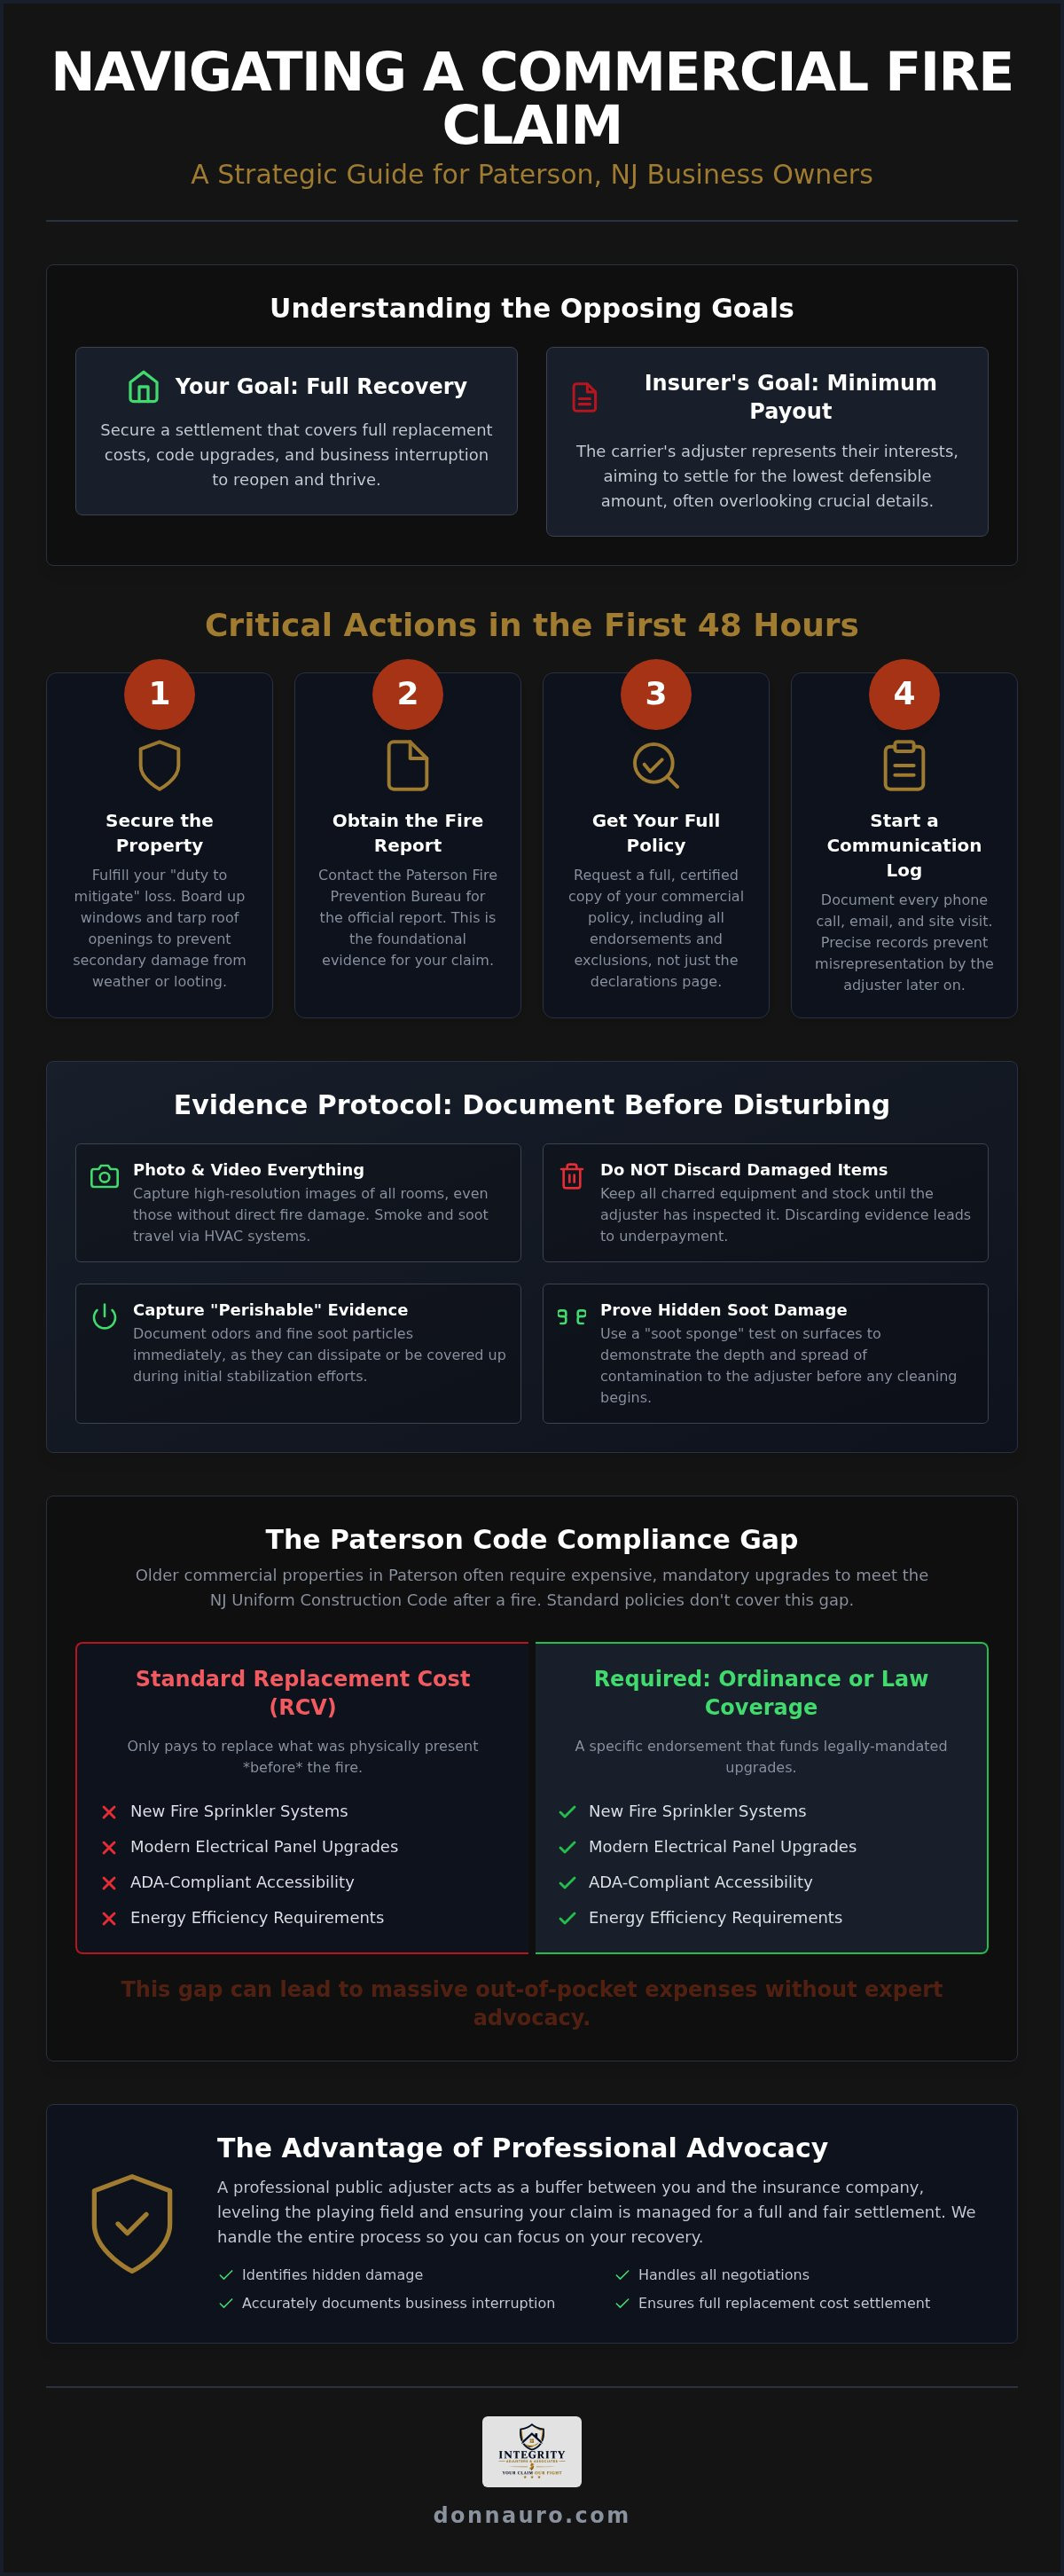
The moments following a fire are chaotic. Decisions made within the first 48 hours will dictate the trajectory of your Paterson NJ commercial fire claim. Your first priority is stabilizing the site. Under most property insurance contracts, you have a "duty to mitigate" further loss. This means you must board up broken windows and tarp roof openings to prevent looting or weather damage. If you fail to take these steps, the insurer might deny coverage for any secondary damage that occurs after the initial fire.
Simultaneously, you must gather objective facts. Contact the Paterson Fire Prevention Bureau to obtain the official fire report. This document serves as the foundational evidence for your claim. You also need a full, certified copy of your commercial insurance policy, not just the declarations page. This document contains the specific endorsements and exclusions that apply to your loss. Finally, start a communication log. Record every phone call, email, and site visit from the insurance company. Accuracy here prevents the adjuster from misrepresenting previous conversations later in the process.
Securing Evidence and Documentation
Don't touch anything until you've documented it. Take high-resolution photos and video of every room, even those without visible fire damage. Smoke travels through HVAC systems and leaves corrosive residues that aren't always obvious at first glance. It's vital to preserve the scene exactly as it was found.
- Keep damaged inventory: Do not discard charred equipment or stock until the adjuster inspects it. Discarding evidence is a common reason for underpayment.
- Capture "perishable" evidence: Odors and fine soot particles can dissipate or be covered up during stabilization. Document these early.
- Document structural soot: Use a "soot sponge" test to show the depth of the damage to the adjuster before any cleaning begins.
Understanding the Notice of Loss
Your policy requires "prompt notice." Delaying the report gives the insurer a reason to question the validity of the event or the extent of the damage. However, you must be careful with your initial words. Insurance companies often request recorded statements immediately after a Paterson NJ commercial fire claim is filed. These statements can be used against you if you haven't yet assessed the full scope of the loss. Focus on the facts of the fire. Avoid speculating on the cause or the total dollar amount until you have professional support. Remember that smoke and soot damage are just as critical as the fire itself. These invisible elements often require specialized cleaning that standard settlements frequently fail to cover.
Navigating Paterson Building Codes and Local Ordinances
Paterson's industrial history defines its commercial landscape. Many properties, from historic silk mills to mid-century warehouses, were constructed long before current safety standards existed. When you file a Paterson NJ commercial fire claim, the damage often reveals a significant gap between your building's pre-loss state and modern legal requirements. The City of Paterson enforces the New Jersey Uniform Construction Code (UCC), which means any major repair must meet current benchmarks for safety and accessibility.
Standard business insurance policies often contain a "Replacement Cost Value" (RCV) provision. However, RCV only pays to replace what was there before the fire. It doesn't naturally cover the cost of adding a new fire sprinkler system, upgrading an electrical panel to 2026 standards, or installing ADA-compliant ramps. Without the right endorsements, you could be left paying for these mandatory upgrades out of pocket.
Ordinance or Law coverage is a specific insurance provision that funds the additional costs required to bring a damaged commercial property into compliance with current New Jersey building codes and local ordinances during the reconstruction process.
The Impact of Age on Reconstruction Costs
Paterson’s zoning laws can be restrictive. If a fire causes substantial damage, the city may require you to rebuild the entire structure to modern standards rather than just repairing the affected area. This creates a massive financial gap between your "pre-loss condition" and a "legal-to-occupy condition." We specialize in documenting this gap. We identify every code-mandated upgrade, from structural reinforcements to energy efficiency requirements, ensuring the insurer doesn't dismiss these as "improvements" outside the scope of the claim.
Working with Paterson Building Inspectors
City inspectors and insurance adjusters often have conflicting goals. The inspector demands compliance; the adjuster wants to minimize the payout. We bridge this divide by coordinating directly with the Paterson Building Department. By securing written documentation of required upgrades from city officials, we force the insurance carrier to acknowledge these mandates as part of the covered loss. If you're facing high reconstruction costs due to local mandates, expert advocacy ensures these expenses are factored into your final settlement, protecting your business from unexpected debt during the rebuild.
Calculating Business Interruption and Soft Costs in NJ
A fire does not just destroy physical assets. It halts your revenue stream. For a Paterson NJ commercial fire claim, the financial recovery depends heavily on your Business Interruption (BI) coverage. This is not just about lost sales. It is about the net profit you would have earned plus the expenses that continue regardless of your operational status. Insurance companies often use generic regional data to project your losses. This approach frequently underestimates the specific market dynamics and historical growth of a Paterson business.
Proving projected revenue is a forensic exercise. Carriers look for reasons to reduce the payout, often citing historical trends or seasonal dips to argue that your losses are lower than claimed. We counter this by building a data-backed narrative of your business's actual performance. If you need more general information on this process, you can find commercial property insurance claim help through our specialized guides. Our goal is to ensure the adjuster’s BI calculation matches your financial reality, not their corporate formula.
Measuring Lost Profits vs. Continuing Expenses
Not all costs vanish when your doors close. You still face property taxes, insurance premiums, and the salaries of key personnel you cannot afford to lose. These are "continuing expenses." We use your federal tax returns and profit and loss (P&L) statements to establish a baseline for these costs. A critical, often overlooked component is the "Extended Period of Indemnity." This endorsement provides payments after you reopen but before your revenue returns to pre-loss levels. Without it, your settlement stops the moment you turn the lights back on, even if your customer base hasn't returned yet.
Documenting Extra Expenses
Recovery often requires spending money to save money. Extra Expense coverage pays for the non-ordinary costs of maintaining operations while your primary site is under repair. This might include leasing a temporary storefront in a nearby Paterson neighborhood or renting specialized machinery to fulfill existing contracts. It also covers the cost of advertising to inform your clients of your temporary status. Every dollar spent to mitigate your loss must be tracked with precise documentation. We ensure these "soft costs" are categorized correctly so they aren't rejected as "unnecessary" by the insurance carrier.
The Advantage of Independent Advocacy in Complex Fire Losses
The insurance company's adjuster is not your partner. They are a professional negotiator. Their primary duty is to the carrier's profitability. Filing a Paterson NJ commercial fire claim puts you in a complex financial dispute. The insurer holds the initial advantage. They have the data. They have the software. They have the experts. Independent advocacy shifts this balance. We act as your strategic ally. We ensure every detail of your loss is documented. We defend your claim against the carrier's attempts to minimize the payout.
A public adjuster is a licensed professional who represents the policyholder’s interests exclusively, while a company adjuster is an employee of the insurance carrier focused on limiting the company’s financial exposure during a Paterson commercial loss.
Why the Carrier’s Estimate is Often Incomplete
Generic estimating software often fails in a local context. These programs use average labor rates. These averages frequently ignore the actual costs of skilled contractors in Northern New Jersey. Industrial losses require specialized knowledge. Standard adjusters often overlook intricate cleaning for high-precision machinery. They miss the corrosive effects of smoke on sensitive electronics. These items must be identified immediately. If they aren't, they won't be in the initial estimate. We perform a forensic inspection. We uncover hidden damage. This includes soot particles embedded deep within HVAC ductwork. It includes structural soot that compromises the building's integrity. Every unlisted item is a cost you will eventually have to pay yourself.
Leveling the Playing Field
Managing a commercial fire recovery is exhausting. The paperwork load is massive. It can overwhelm even the most organized business owner. We handle the documentation. We handle the meetings. We handle the aggressive negotiations. This creates a necessary buffer. It protects you from the pressure tactics adjusters sometimes use to close files quickly. This allows you to focus on your employees. It lets you focus on your customers. While this guide focuses on fire, you can also see our guide on residential water damage claim support for general claim tips. Professional loss documentation allows us to counter the insurer’s experts. We use facts they cannot ignore. This methodical approach is the only way to move from a low-ball offer to a fair settlement. If you are struggling with a complex claim, contact our expert advocates today to protect your business’s future.
Expert Commercial Fire Claim Support in Paterson, NJ
Recovery starts with precision. Integrity Adjusters & Associates provides the expert advocacy needed to manage a Paterson NJ commercial fire claim from the initial site stabilization to the final settlement check. We don't just file paperwork. We act as a professional buffer between your business and an insurance system designed to protect corporate profits. Our team understands the specific pressures of the New Jersey insurance landscape, allowing you to focus on your employees and operations while we handle the technical complexities of your loss.
We offer no-obligation claim reviews for businesses that have already received an initial offer. Many owners find that their carrier has overlooked critical items or used generic data that doesn't reflect the reality of the Paterson market. We identify these gaps. We build the evidence required to reopen underpaid files and secure the full replacement cost your policy promises. Our goal is a settlement that reflects the true scope of your damage, including the invisible soot and business interruption losses that standard adjusters often ignore.
Our Process for Paterson Businesses
Our methodical approach brings order to the chaos of a fire loss. We follow a structured, three-phase system to ensure no detail is missed during the recovery process.
- Phase 1: Policy Analysis and Site Inspection. We perform a deep-dive review of your insurance contract to identify every available endorsement. This is followed by a forensic site inspection to document physical damage and environmental contamination.
- Phase 2: Detailed Loss Estimation. We create a comprehensive estimate using local Paterson labor rates and material costs. This phase includes a forensic calculation of your business interruption losses based on your actual historical performance.
- Phase 3: Vigorous Negotiation. We present our documented evidence to the insurance carrier. We manage all meetings and correspondence, countering their experts with facts to push for a fair and timely resolution.
Secure Your Settlement Today
Waiting to hire an advocate can hurt your claim's momentum. The insurance company's experts are on-site within days, building a narrative that favors the carrier. By involving us early, you ensure that the "Integrity" of your documentation is established from the start. We record every loss accurately, preventing the carrier from dismissing valid claims later in the process. We don't accept low-ball offers, and we don't let our clients be pressured into premature settlements. Your business’s survival depends on a complete financial recovery. Contact Integrity Adjusters & Associates for Paterson NJ commercial fire claim support to begin building your comprehensive recovery plan today.
Protect Your Business with Strategic Recovery
A successful Paterson NJ commercial fire claim requires more than just reporting a loss. It demands a disciplined approach to documentation and a deep understanding of local building ordinances. We've seen how easily insurance carriers overlook business interruption costs or the expensive reality of modern code compliance. Without a professional advocate, these hidden gaps often lead to settlements that fail to cover the true cost of reopening. You don't have to navigate this institutional system alone.
Integrity Adjusters & Associates has specialized in NJ commercial loss since 2026. As comprehensive documentation experts, we act as your dedicated shield; we ensure every soot particle and lost revenue dollar is accounted for. We handle the aggressive negotiations so you can focus on leading your team back to operational stability. Our methodical process is designed to bring order to the chaos of fire damage. Don't leave your financial future to the insurer's generic estimates. Get Expert Advocacy for Your Paterson Commercial Fire Claim today. Your business is resilient, and with the right support, your recovery will be too.
Frequently Asked Questions
What is the first thing I should do after a fire at my Paterson business?
Stabilize the property and notify your insurance carrier immediately. You have a contractual duty to mitigate further loss; this includes boarding up broken windows and tarping roof openings to prevent weather damage or looting. You should also contact the Paterson Fire Prevention Bureau to obtain the official fire report. Promptly initiating your Paterson NJ commercial fire claim ensures you meet the strict reporting deadlines found in most policies.
Can I clean up the fire damage before the insurance adjuster arrives?
You shouldn't perform any cleanup beyond basic mitigation steps. It's vital to document the scene exactly as it was found using high-resolution photos and video. Discarding damaged inventory or cleaning soot residues before a professional inspection can lead to the insurer underestimating your loss. Preserving evidence allows us to build a comprehensive claim that reflects the true scope of the physical and environmental damage.
Does my commercial insurance cover Paterson city code upgrades?
This depends on whether your policy includes Ordinance or Law coverage. Standard replacement cost provisions only pay to restore what existed before the fire. However, the City of Paterson enforces the New Jersey Uniform Construction Code. This often mandates expensive upgrades to ADA compliance, electrical systems, or fire sprinklers during reconstruction. We review your endorsements to ensure these mandatory municipal costs are factored into your final settlement.
How long does a commercial fire claim settlement typically take in New Jersey?
Timelines vary based on complexity, but New Jersey law establishes specific requirements. An insurance company must begin its investigation within 10 days of receiving a claim. They generally have 30 days to complete the investigation once you provide a properly completed proof of loss. If the carrier denies the claim or requires more time, they must notify you within 45 days. Once a settlement is agreed upon, payment is due within 10 days.
What is the difference between a public adjuster and the insurance company’s adjuster?
A public adjuster is a licensed professional who works exclusively for you, the policyholder. The insurance company's adjuster is an employee or contractor for the carrier; their primary goal is to protect the company's financial interests and minimize the payout. Public adjusters act as your strategic ally. We handle the documentation and negotiations for your Paterson NJ commercial fire claim to ensure the settlement covers your actual losses.
Will my insurance rates go up if I hire a public adjuster for my Paterson fire claim?
Hiring a public adjuster is a contractual right and doesn't typically cause a rate increase on its own. Insurance premiums are generally influenced by the fire event itself and regional risk factors in Northern New Jersey. Professional advocacy ensures your claim is handled accurately from the start. This reduces the risk of long-term financial loss and ensures you receive the funds necessary to restore your business operations correctly.
What if my commercial fire claim has already been denied by the insurer?
A denial isn't always the final decision. We perform no-obligation reviews of denied claims to identify errors in the insurer's investigation or policy interpretation. If the carrier overlooked evidence of damage or misapplied a policy exclusion, we can reopen the file. We present a data-backed case to dispute the denial and push for a fair resolution. In New Jersey, you have the right to challenge unfair claim decisions.
How do I calculate lost revenue for a business interruption claim?
You must use historical financial records, including federal tax returns and profit and loss statements. The calculation includes the net profit your business would have earned plus continuing expenses like rent, taxes, and key employee payroll. We perform forensic accounting to ensure your claim reflects your actual performance. This prevents the insurer from using generic regional averages that might underestimate the specific growth and seasonal trends of your Paterson business.


